Roof insurance claims in Flower Mound
Separate the roof’s repair needs from the policy’s coverage, deductible and depreciation rules. See how a hypothetical claim payment can unfold.
Free roof inspections for homes and commercial properties.
Understand the payment without guessing at coverage
A roof inspection addresses physical condition and the work needed. An insurance claim addresses whether the policy covers a loss and how much it pays. Those questions connect, but one does not answer the other.
The examples here explain payment mechanics, not a result for your roof. The policy, insurer’s estimate, covered scope and completed work determine the actual amounts. Ordinary age and wear do not create an automatic entitlement to a new roof.
Roof damage, coverage and your deductible
Damage and coverage
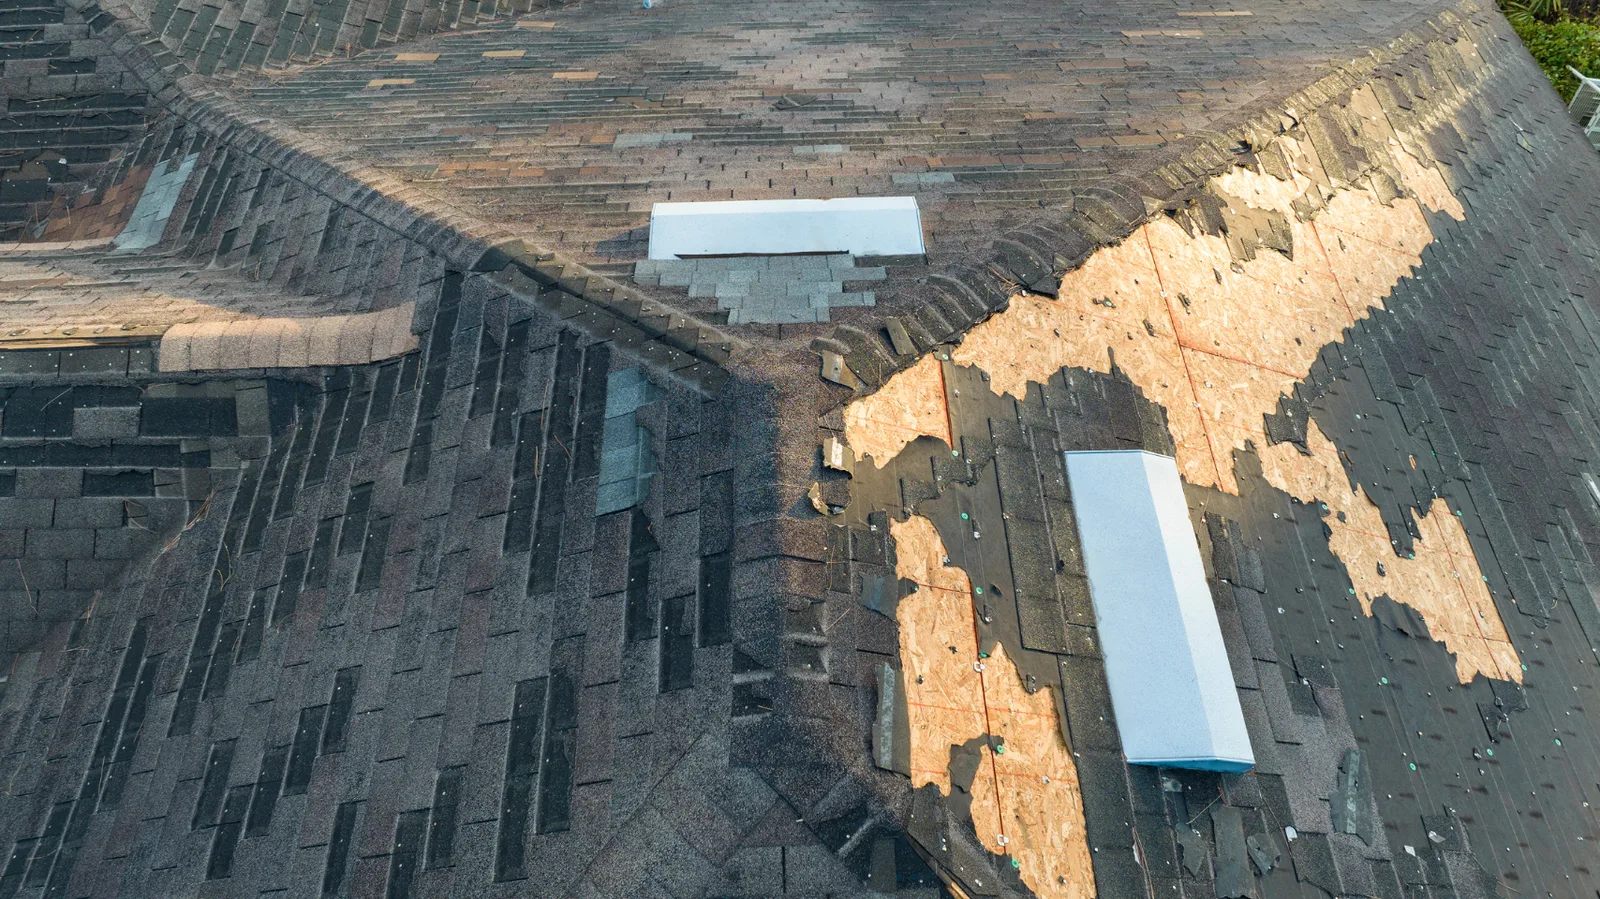
Wind or hail damage needs to be distinguished from deterioration. The insurer applies the policy’s terms, exclusions and limits to the reported loss.
The deductible
This is the portion of a covered claim the policyholder pays. A wind/hail deductible may differ from the deductible for another cause. A percentage deductible can be based on the insured dwelling amount rather than the repair bill.
Depreciation
Actual cash value accounts for age and condition. Replacement-cost coverage can involve an initial payment reduced by depreciation and a later eligible payment after the policy’s repair requirements are met.
How depreciation changes a claim payment
Hypothetical covered loss only: $15,000 accepted replacement cost, $4,000 depreciation and a $2,000 deductible. These numbers are chosen to explain the arithmetic, not to estimate a Flower Mound roof.
- Accepted replacement cost
- $15,000
- Less depreciation
- − $4,000
- Less deductible
- − $2,000
- Illustrative initial payment
- $9,000
If the policy allows recovery of that depreciation and its repair and documentation conditions are met, an additional $4,000 could bring the example’s insurance payment to $13,000. The owner still pays the $2,000 deductible.
Under an actual-cash-value settlement with no recoverable depreciation, that $4,000 would not become a later payment. Upgrades, uncovered work or differences in the accepted scope can also change the owner’s final cost.
What roofing help and insurance each decide
- Roofing scope
The roof assessment addresses the failed components, affected materials and work needed for a lasting repair or replacement. It does not decide policy coverage.
- The insurer’s decision
Coverage, depreciation, deductible and claim payments come from the policy and insurer’s handling of the claim. No approval or payment amount is promised here.
- The owner’s project
The project agreement should identify the roofing work and price. A claim estimate and a contractor’s scope are different documents; neither makes unspecified upgrades free.
Keep the policy’s deadlines in view
Reporting, proof-of-loss, repair and depreciation-recovery requirements depend on the policy and claim. No universal deadline is stated here. The insurer or agent can explain the requirements for the particular policy.
The Texas Department of Insurance roof guide explains roof coverage and staged payments. Its home insurance guide gives the broader deductible and depreciation context. Sources checked September 21, 2026.
Start with a free roof inspection
Tell us about the damaged area or leak. A free inspection can clarify the roof’s condition and physical repair needs while coverage is considered separately.
Call (469) 240-3513